TTA’s Fall Follies: Anthropic breaks the record, Oracle’s Sicilia and Verma get House beatdown, big raises for Hone Health, Zus Health, GrandCare for I/DD mobile support, more!

20 – 23 November 2026

It must be the pre-Thanksgiving (next week!) rush, because the wires this week were jammed with Big News.

For Mr. Market, it was the smashing Anthropic IPO–yet it couldn’t pull AI out of the doldrums. For Oracle, it was a Bad Week in Foggy Bottom as both their executives were pummeled in the House Committee on the EHRM extension and the nerve to actually get paid for it. (A time when both should have had numbers on hand.) A concierge longevity teleplatform, Hone Health, mustered a 2020-worthy Series A/financing as did Jonathan Bush’s Zus Health. GrandCare debuted a mobile app extending their tech to the intellectually and developmentally disabled. In less cheerful news, Heidi Health reorganized and let go 18%, while in NY DocGo’s Ambulnz had more layoffs.

Next week will be a short week at the desk for your Editor, so updates will be few unless Big News.

Please feel free to comment on the articles and pass along this Alert. Let me know if this is worth it to you! Also check out my personal page on Substack.

News roundup: Anthropic breaks records, Hone Health’s $228M raise, Heidi Health’s woes, Aevius spins out with $22M

Oracle’s Sicilia and Verma meet the House Committee on Veterans’ Affairs, do some ‘splainin’, get bashed and some surprises (They’re in it till 2031, but was it worth the beating and the threats?)

Oracle’s Sicilia, VA’s Evans do some ‘splainin’ to the Senate VA Committee (Apparently not as bad as the House)

Short takes: DocGo’s Ambulnz lays off in NY, Zus Health’s $33M raise, Inovalon to buy DrFirst, GrandCare launches Companion App for I/DD market

Big Wednesday, vol. 2: Oracle’s Mr. Sicilia Goes to Washington (again) to do some ‘splainin’

Big Wednesday, vol. 1: Anthropic to price IPO Wednesday, ANT to trade Thursday (updated)

Ageing In Place: UKTelehealthcare webinar Wed 18th 10.00-11.30am GMT (While past, a quick look at what UKTelehealthcare is now up to)

Last week

The week that was in AI, more opinions on the Anthropic IPO, and a Must Read on “The End of the World as Business Model” 

M&A/Funding news roundup 11/11: Oura’s big buy of Counsel before IPO, XRHealth buys PursueCare and Living Brain, Charta Health’s $55M Series B

More Of Interest 

Weekend Must Reads: Polevikov on Walmart’s Ninth Try At Health with General Medicine, Zitron on the Collapse of the AI Bubble

More questions for Oracle as VA doctors and dentists question EHR rollout safety, demand a pause; Oracle’s $20B AI building raise

Developing: Walgreens’ Sycamore Partners owner on final approach to sell Boots operation to Canada’s Weston family for ~$9B

Oracle’s continued restructuring cuts 3K more jobs, adds $700 million while revenue grows 30%; House VA Committee subpoenas Ellison, Sicilia 19-0–and why Congress is mad at a 170% budget increase (Updated for how Congress really feels)

AI’s hoofbeats as Horses, not Zebras: a Gimlety view of AI’s destructive capacity (updated) (P(doom) may be conquered by F(doom), or Why Worry?

 * * *
Advertise on Telehealth and Telecare Aware
Support not only a publication but also a well-informed international community.

Contact Editor Donna for more information.

Help Spread the News

Please tell your colleagues about this free news service and, if you have relevant information to share with the rest of the world, please let me know!

Donna Cusano, Editor In Chief
donna.cusano@telecareaware.com

News roundup: Anthropic breaks records Thursday–suffers hangover Friday, Hone Health’s $228M raise, Heidi Health’s woes, Aevius spins out with $22M (updated)

To no one’s surprise and to the benefit of your portfolio should you have one, even if all in mutual funds, Anthropic and Mr. Market partied all day. ANT started the day at 11.30am ET at $83/share, peaked at $111.50 per share, and closed at $97.17 which is a 17% first day gain. It was the largest first day ever in the history of the US markets. Anthropic raised $81.3 billion with a new valuation of $1.5 trillion. Over at the financial channels, the partying was like 1999. (No TV in 1928). Yet the Dow Jones closed below 50,000 for the first time since June. AI and chips are still in the doldrums and ANT didn’t much change that. Where’s Prince now for the soundtrack? Yahoo Finance, CNBC

Update: But the hangover hit on Friday. ANT stock continued its cruise down to the opening price levels ($83.23 as of 12.48pm ET). There are widespread predictions that the plummet will continue. ANT is not immune to the AI international selloff, powered by the Huang exit from Nvidia. In the view of some observers, it accelerated the AI bubble bursting.

For existing ANT investors who exited as the price rose and by yesterday’s close, they are having muscle strain from patting themselves on the back. For internal shareholders who can’t do anything other than watch, this is one bad day, but at least they can tell themselves they can do nothing. For those who bought at $83, start praying. Sadly, this is all too common an IPO pattern but accentuated by the sector’s weakness. [Editor’s Note: None of the above or links included should be construed as investment advice nor as recommendations as to advice providers.] Marcus on AI, Yahoo Finance

CNBC’s updated roundup confirmed that the raise was $93.5 billion. Anthropic underwriters exercised the “greenshoe” over-allotment of shares. A “greenshoe” is an over-allotment option, typically 15% more than a baseline. In this case, Anthropic exercised the sale of an additional 147 million shares today, bringing the sold total greenshoe to 1.127 billion shares. ANT release

Consumer longevity platform Hone Health raises $228 million. Their financing structure is interesting and a little complicated. The current financing led to a reveal of a previously undisclosed Series A, with $28 million raised as an extension of the Series A and the remaining $200 million as growth financing from General Catalyst’s Customer Value Fund (CVF). The lead for the Series A is MarcyPen Capital Partners, with additional participation from Pentland Ventures, Kinship Ventures co-founded by Gwyneth Paltrow and Moj Mohdara, Hanwha, Gannet Capital, humbition, Comma Capital, and ID Ventures. The new funding will be used in five areas: broader clinical care, advanced diagnostics, clinical technology, emerging therapies, and research and trials. A basic biomarker test starts at $65 and is not covered by insurance. Most of their services are available only to members, which start at $25/month (Basic), $135/month (Plus), or $155/month (Premium). Release, MedCity News

Their other big launch is Hone Black, a concierge platform emphasizing whole body care and a select team of doctors. That will run the eager longevity maven $1,250 per month, billed annually at $15,000 per year. With an endorsement from Gwyneth Paltrow, who despite Goop is a savvy moneymaker, one can suss out that Hone is one of those very elite services Not For The Masses.

Australian practice scribe/documenter Heidi Health has fallen into a few mountain crevasses. The Melbourne-headquartered global company laid off 18% of staff (108 of approximately 600 employees). The layoffs come a day after cofounders Waleed Mussa and Yu Liu departed the company as planned. Dr. Thomas Kelly will remain as CEO in the restructuring which is cited as improving alignment of staffing and investment with company growth priorities, an otherwise anodyne statement. 

Ironically, in September Heidi had successfully landed a A$475 million financing package consisting of a $100 million Series C round and a separate $240 million growth financing facility. September also marked the launch of AI agents to plan and execute tasks such as pre-charting, referral communications, panel reviews and follow-up work across EHRs, calendars, inboxes and patient portals. The layoffs affect customer service, which will move into product teams, and R&D will be reorganized. There is no word on what areas of the global operation will be most affected. Mobihealthnews, HLTH

Aevius launches with a $22 million seed round investment. The Mass General Brigham spinout for clinical intelligency was financed by Insight Partners. The platform creates AI models that turn structured, unstructured, and “specialty multimodal” clinical data from healthcare, payer and life sciences organizations into useful information for them, across different systems, formats and medical vocabularies to build a comprehensive picture of each patient. Potential uses include care planning, population analysis, biomarker identification and clinical trial recruitment. The funding from Insight Partners will be used for continued model and product development, expansion of the company’s engineering, clinical and commercial teams, and commercial deployment. Release, Mobihealthnews

Oracle’s Sicilia and Verma meet the House Committee on Veterans’ Affairs, do some ‘splainin’, get bashed and some surprises (updated)

The second VA Congressional hearing for Oracle was a sad and barely dignified bash fest. Based on a view of the 2+ hours of the hearing on YouTube, the 25 Members of the House Committee on Veterans’ Affairs this morning had no mercy. CEO Mike Sicilia and General Manager of Oracle Health Seema Verma stuck to their story but fumbled their numbers. Faced with a properly critical Republican Chair (Mike Bost) and a Democrat ranking member (Mark Takano) who improperly used his time mostly to bash President Trump’s rich friends such as Larry Ellison, which was not the purpose of the session, one could not be blamed at the outset for not wasting time you’d never get back.

Supposedly this was about Oracle, VA, and the future of the EHRM rollout, including the extension to 2031 and the budget request for an additional $17 million. It was titled “Beyond Go-Live: VA Electronic Health Record Modernization Status Update”. It wasn’t.

This is a selective view, based on viewing most (but not all) of the video, and examining facts as covered previously.

It surely does not help that Mr. Sicilia, with shaved head and wispy moustache/goatee like a dinner theatre version of Superman’s Lex Luthor, got off to a shaky start. He hoarsely read from a prepared statement at the opening. He fluffed his answer to Rep. Brownley (D-CA) who asked him about his 2022 statement about absorbing the cost overrides. He pointed to all the free builds Oracle provided (see TTA 17 Nov, 18 Nov). What he did not do was stick to the solid points of a contract expiring in 2028, an extension, the acquired Cerner EHR failing, and VA’s wider scope for the EHRM as it rolls out. With the same representative, Seema Verma fluffed numbers of the dollar value of what Oracle did absorb, making for a near-perfect ‘gotcha’ for this Member. No wonder Brownley was smiling. The gotchas and the baiting were so evident that at about 1:12, Chairman Bost had to tell Members to not deal with the “personalities of the President” and warning that Members took “the same political contributions”.

Both Sicilia and Verma were weak on financials, a sore point when you are discussing a $17 billion spend increase.

Two physician members wasted time in a side issue, comparing Cerner/Oracle EHR implementation at the Military Health System (MHS) to the VA’s (1:29). VA is far larger (170 hospitals) and requires far more features than MHS’ 51 hospitals plus clinics that deal with active service members with a narrower set of medical needs.  MHS also had a two year head start and largely closed the transition last year. 

Republican Rep. Van Orden was equally savage at 1:33. He scored Oracle on the system failures, “corruption”, lobbying (see below), and paying other companies to sue Epic. He closed with a demand to “sever” Oracle and turn it over to a ‘commercial system,’ namely Epic. Again, neither Sicilia and Verma didn’t have numbers to hand in what predictably was a financial discussion. (See below re Epic)

Verma also denied that Oracle was using veteran data for AI purposes. “We have zero access to the data of the veterans,” Verma said. “We have testified multiple times. We have no access. We do not use that data for any purpose. It is only used by the VA to deliver care for veterans.”

The rest of the Representatives engaged in name calling, fact distortion, and hilarious fiction, such that men like Andrew Carnegie and John D. Rockefeller were selfless, do-gooding moguls during their business careers, in contrast to Larry Ellison.

The big surprises are towards the end. Ranking Member Takano finally drilled down to a good solid line of inquiry, one this Editor would ask if I were in his chair.

Surprise #1: He asked asks Mr. Sicilia if Oracle is going to sell or spin off Oracle Health or the EHR business, including whether Oracle has retained investment banks, consultants, and law firms to explore this. The denial was flat: “we have not”. This was then followed by some fumfering as Mr. Sicilia realizes he is speaking about a public company 40% owned by the chairman. Rep. Takano then moved on to the ‘have you ever spoken with…” which was answered by Mr. Sicilia with some verbal ‘iffyness’ but then….

Surprises #2 and #3:  …a flat commitment by Oracle to sustain the EHR implementation through 2031, the point of the extension. Sicilia  also confirmed that Larry Ellison was not involved in VA negotiations, which Rep. Takano tried to negate through Mr. Ellison’s connections with President Trump.

Here is where grandstanding and Blame Game hurts veterans and does not help the goal of an working, interoperable EHR. Ranking Member Takano opened by blaming President Trump for the formal Cerner contract award in 2018 (announced June 2017). For those of us who prefer facts and dates, the timeline says something else over three administrations, Democrat and Republican, from 2015 on. House and Senate staffs would be well advised to look below to brief their Members:

  • The Military Health System (MHS) had awarded its contract to Cerner in 2015, two years earlier. (Obama Administration) In other words, Cerner was an incumbent of sorts. By 2017 MHS GENESIS was underway to transition MHS from AHLTA. Recap of GENESIS, Leidos, and other vendors here.
  • The Cerner contract was worked on and largely agreed to well before Trump took office in January 2017. The Secretary at that time, who lasted a year, was David Shulkin, who was an Obama appointee as Under Secretary in 2015 having previously been the president of Morristown (NJ) Medical Center. He was appointed Secretary and confirmed by the Senate in 2017 under the Trump Administration to head the VA.
  • Trump said nice things about the Cerner award in 2017 and 2018 for good reason. The award came after over a decade of dithering and billions of dollars of wasted effort in attempting to make MHS with AHLTA and VA with VistA interoperable, as well as modernizing VistA [‘Pondering the Squandering’, July 2013]. Your Editor was not only writing about it, but shortly thereafter was employed by Viterion, at that time a VA contractor for remote patient monitoring. Transitioning VA into a modern EHR, bringing over VistA, being interoperable, and training thousands of VA staffers were all major issues we knew about for contract renewal of our independent system that used VistA data.
  • In 2017-18, Trump and Secretary David Shulkin were largely working with Obama-era or early Trump-era appointees at the VA. There were serious failures there as well, such as executive director John Windom who joined as EHRM team lead in 2017 after working on the MHS implementation while in the Navy. He is now Federally indicted on three counts around failing to disclose cash and gifts from vendors, then making false statements to investigators in failing to report those gifts, plus much, much more. [TTA 3 Apr] Dr. Shulkin was another failure; he lasted a little over one year and was dismissed in March 2018 over ethics issues.
  • Implementations started in 2020. VA Mann-Grandstaff blew up while Cerner still was independent, between late 2020 and hearings in July 2021 [TTA 28 July 2021, 18 May 2022]. Oracle’s buy offer was six months in the future from July.
  • It wasn’t till late December 2021, well into the Biden Administration, that Oracle announced their offer to buy Cerner and ‘the transformation of healthcare’. Some of us viewed the buy, right before Christmas, as a pandemic-driven, $23 billion Lump of Coal. But Oracle did not hesitate despite needing extra financing for it.
  • It went through the usual DOJ, FTC, SEC, and EU reviews and closed with little controversy six months later, on 8 June 2022. Oracle already knew the problems, but the closing legally was when Oracle got the keys to Cerner and really started getting into the mystery and misery package they bought. Yes, Cerner was bought by Oracle and ‘Trump friendly’ Larry Ellison. Yet there were no DOJ or FTC impediments to a speedy closing during the Biden Administration. Funny, that.
  • Oracle, of course, is a long time Federal software vendor under multiple administrations. Larry Ellison wanted to aggressively move into healthcare at that time, and as 40% owner it has always been hard to argue with him. One could argue that Cerner wasn’t the best buy though.
  • The building VA EHRM disaster in the Cerner system that started with implementations in late 2020 was on the record and in Congressional hearings for months. It blew up even bigger by July 2022. That was six months after Oracle’s offer to buy but a scant one month after the close. Oracle was aware of it, but both Oracle and VA were concentrating on the five rollouts to date and trying to fix the rolling disaster.
  • The entire rollout was stopped by VA nine months later on 21 April 2023. It didn’t resume till April 2026. It took that long to fix and update the EHR. Those efforts are all on the record between VA and Oracle.

To blame Oracle for Cerner’s and VA’s implementation while Oracle did not own the company (2020-2021)? Then tried to fix a system they didn’t create? Idiotic. Inaccurate. Irresponsible. And tiresome. Beating a dead horse comes to mind. A simple timeline, researchable here and through AI, uncovers apolitical truth. There is enough blame to go around.

Now to today. Did this House session provide a worthwhile update on the EHRM’s progress and clarity on the increase in spending? NO. Most of the discussion centered on rehashing the past failed implementations of 2020-23 and bashing Oracle for asking for more budget for three more years. The $10 million is just about spent. Oracle is getting no more until after May 2028. VA’s role, in the parts I listened to, was carefully avoided. Other than Oracle’s continued commitment, no House member I observed chose to be the voice of reason on the extension, the scope creep, and logic behind the increase. And VA? Absent. Why?

It was far easier for the Members to beat up Oracle on the past, not the future. Oracle was unfairly blamed for Cerner failures that happened before the purchase closed and tried to fix after. They bought into a disaster. Fair, no. Political, yes.

Why does this matter? The House is more important than the Senate is that the House holds the budget purse strings. They can force, if they like, a complete suspension of further EHRM implementations as they did three years ago. If Rep. Van Orden had his way, VA would be forced to terminate Oracle and hire Epic. In fact, Epic has always had a foot in the door with VA from the beginning, with responsibility for the design of the scheduling module awarded at the same time as Cerner had the main contract. LinkedIn That would assume, of course, that Epic would even have the desire to take on the VA and pick up the entire EHRM contract. Strangely, back in 2017, and with MHS in 2015, they were never mentioned. It is well known that Epic, smartly, avoids Pyrrhic battles. 

Oracle, as a long time Federal software vendor, has generously spread its political/lobbying money between both parties. If Mr. Sicilia is to be believed, Larry Ellison has avoided the VA. But retaining lobbying entity Duddington Global Strategies and its founder/principal Brendan Belair this past summer, according to a disclosure filing, isn’t a good look. Mr. Belair worked close to 10 years for VA Secretary Doug Collins while Mr. Collins was still in the House, and most of this time as his chief of staff. Politico

With a change in party control, it serves the Democrats assuming control in January to blow Oracle’s VA EHRM to the proverbial Kingdom Come. Do not be surprised if there is no further EHR rollout in 2028, for political, not operational, reasons.

See also today’s FedScoop.

Hat tip to a Reader who wishes to remain ‘behind the scenes’.

Oracle’s Sicilia, VA’s Evans do some ‘splainin’ to the Senate VA Committee

Today’s Big Wednesday afternoon before a Senate Committee, sharpening its claws, but no bombshells detonated. As expected, both Oracle CEO Mike Sicilia and VA’s Neil Evans of the Electronic Health Record Modernization (EHRM) Integration Office testified before the Senate Veterans’ Affairs Committee. The position that both are taking is simple: the size, scope, timeline, and the product changed. Thus the price increase. 

The Sicilia statement available here is a 12 page summary nearly identical to the House statement [TTA 17 Nov], frontloaded with the successes of the 2026 deployments, the need for the extension, and the path forward that included Oracle retaining some functions that the Cerner scope turned over to the VA. The testimony had a few surprises, including that over the summer, VA and Oracle negotiated the contract and VA reduced the $18.5 billion Oracle request to under $17 billion. Bloomberg Government reported that the negotiations were entirely via email; a VA spokesperson told Becker’s that the ceiling “was negotiated through a series of virtual and in-person meetings.” The FedScoop report also had Sicilia’s live statement updating the interface increase to 190 (versus 164 and the original 57) and that some of the rising costs could be pinned on COVID-19 pandemic-related delays, customizations and “inadequate infrastructure from Cerner that impacted system stability”. 

Carol Harris of the GAO outlined VA’s estimate, sans the underlying analysis which she said that VA has held up for a year. 

  • $37.2 billion is the full lifecycle cost estimate to go live at all 170 sites by 2031
  • An additional $19.3 billion to operate and sustain the system for another decade
  • Total: $56.5 billion.

This contrasts to the Sept. 2 House hearing where VA Deputy Secretary Paul Lawrence estimated about $11 billion for sustainment, for roughly $48 billion total. The difference is $8 billion. Responding to Ms. Harris, committee Chairman Jerry Moran (R-KS) said, “Why do you need an agreement? Just do it.”

Retired (by the voters) lame duck Senator Thom Tillis (R-NC) reenacted the Short-Timer Skunk at the Picnic by accusing VA and Oracle of a failed execution and of a four-fold increase in project cost. The reality is that the extension and changes increased the Oracle budget by 1.7x to $27 billion. He used the $37.2 billion lifecycle cost instead.

More tomorrow when Sicilia and Verma (who hasn’t left yet, versus reports over the summer) Face The House. FedScoop

Short takes: DocGo’s Ambulnz lays off in NY, Zus Health’s $33M raise, Inovalon to buy DrFirst, GrandCare launches Companion App for I/DD market

DocGo cuts back after acquisition. Back in August, the parent company of Ambulnz medical transportation/standby EMT services bought Hicuity Health, assuming $52 million in debt and $50 million in external debt financing via Perceptive Holdings. Now Ambulnz has filed WARN notices for layoffs in New York State under its business entity Ambulnz NY2, LLC. The layoffs are across nine upstate and largely rural counties, with permanent closures at 11 sites, covering 85 workers, starting 31 December. The largest are in Newburgh (36 workers) and Rensselaer (20).

Hicuity is a provider of high acuity virtual clinical care including tele-ICU, virtual nursing, and telemetry monitoring services for rural health systems, hospitals and post-acute facilities. It is planned to be integrated into Ambulnz Holdings. The layoffs above, which are largely in rural counties, is puzzling though. Money Tracker Daily   Hat tip to Ahsan Mustafa, editor of Money Tracker Daily

Zus Health’s Series B raises $33 million. The fresh financing will assist in additional development of its intelligent patient record platform, national healthcare data network, and AI-powered clinical workflows. The total funding for the Jonathan Bush-founded and led company is now over $100 million. The Series B was led by Drive Capital, with participation from Sanofi Ventures, HealthX Ventures, and Alumni Ventures, as well as existing investors Andreessen Horowitz (a16z), F-Prime, Maverick Ventures, and JAZZ Venture Partners. Release, Mobihealthnews

Inovalon to buy DrFirst. It’s definitely a large ‘bolt on’ acquisition that increases Inovalon’s size and reach substantially. Inovalon specializes in healthcare data and analytics, while DrFirst is a medication management and workflow solutions provider with AI integrations. For Inovalon, the acquisition will increase patient access to provider, pharmacy and patient engagement as well as additional data. The combined organization will have 2,000 hospitals and 240,000 prescribing providers writing 241 million+ prescriptions a year across 270+ EHR integrations. The purchase price was not disclosed. The release does not disclose organizational integration.

GrandCare Systems debuts Companion App for an underserved market. That market is individuals with intellectual and developmental disabilities (I/DD). The Companion App adapts GrandCare’s established remote support platform for the disabled from the in-home screen to Android and iOS smartphones. For I/DD individuals, the Companion App assists with their daily routines, learning new tasks, and connecting with their disability service and support teams to help them live more independently as well as safely. GrandCare is one of the earliest pioneers in tech-based telehealth, health monitoring, and socialization for senior care–and while this Editor knew them from her health tech salad days in marketing for Living Independently/QuietCare, one thing I didn’t know was their ‘line extension’ to I/DD services. Release

Big Wednesday, vol. 2: Oracle’s Mr. Sicilia Goes to Washington (again) to do some ‘splainin’

To paraphrase the underappreciated business genius Desi Arnaz, Mike has some ‘splainin’ to do. Tomorrow (Wednesday 18 Nov) at 4pm ET is the day that Mike Sicilia, Oracle’s CEO, will be facing the US Senate Committee on Veterans’ Affairs. He will be accompanied by Seema Verma, EVP/General Manager of Oracle Health and Life Sciences. The topic? VA Accountability and Transparency: Examining the Current and Future Path of VA’s Electronic Health Record Modernization Program. Also on the hot seats: Neil Evans of VA’s Electronic Health Record Modernization (EHRM) Integration Office and Carol C. Harris, director, Information Technology and Cybersecurity, U.S. Government Accountability Office (GAO). Interestingly, the Senate page on the hearings has no agenda nor live link, only a witness list of Messrs. Sicilia and Evans with Ms. Harris.

No rest for the weary, as the parallel full House Committee on Veterans’ Affairs is seeing Mr. Sicilia at 10 am on the following day, Thursday 19 November. The House Committee made no secret of its feelings as he was subpoenaed in a 19-0 vote with a second subpoena for chairman Larry Ellison. Mr. Ellison’s appearance will follow on Thursday 10 December. There is no listing for a Senate hearing at this time.

The House Committee list of witnesses is on a second linked page. Unlike the Senate, there are no VA witnesses, only Mr. Sicilia and Ms. Verma. There is a statement by Mr. Sicilia here that reviews the problems, the resumption of implementations, and why the increase beyond the extension. Stoutly stated is that there has been no repricing the original baseline costs on the original term. Spending is controlled by task order in this Indefinite Delivery Indefinite Quantity contract. On page 7-8, the points made to justify the increase are summarized as “requirements and capabilities that had not been defined, sized, or priced in the original program assumptions”. From the statement:

  1. VA has increased the number of interfaces from the original contract from 57 to 164 (a 187% increase)
  2. It expanded the system’s capacity to manage longitudinal veteran health data from 8 million to 26.1 million records (a 226% increase)
  3. The number of concurrent users increased from 85,000 to 195,000 (a 129% increase).
  4. The 2018 contract also assumed that VA would take over several recurring functions at defined points, which has not happened.

There is also some finger pointing at Cerner’s specifications for the EHRM contract.

He noted that Oracle has also provided at its own cost:

  • Oracle’s new Pharmacy Reimagine 7 module that is anticipated to go live next year
  • The advanced interoperability Qualified Health Information Network (QHIN) so that veterans can have strong interoperability when receiving care in the community
  • The migration of the EHR from the on-premises data center to Oracle Cloud Infrastructure (OCI) and the associated cybersecurity protections and modern platform that Oracle Cloud provides
  • Plus 4,700 configuration changes 

It is to be seen whether Mr. Sicilia’s arguments will be convincing or challenging to a rump session of the House which is about to change political party control, with the usual concomitant posturing and preening. Usually, the latter overrides the former. Those with high tolerances can go to the House page to see it livestreamed.

A short backgrounder: Our Readers know from our prior report two months ago  that what has made both houses of Congress Madder Than The Wet Hens They Are is that in August, VA tried to slip in a $17 billion increase in budget for Oracle’s EHR development under the cover of a three-year extension to May 2031. The original Cerner (pre-Oracle takeover) estimate was a $10 billion ceiling for a timeline that ended in May 2028. [TTA 17 Sept] Mr. Sicilia’s problem? On 20 July 2022, in his then-role as EVP for Industries, he told the Senate committee that Oracle would absorb any “performance or workflow” issue costs above the original $10 billion ceiling–words that we’d bet he’d wish to retract. What’s worse: Members supposedly found out about the increase via news reports issued in August’s Dog Days [TTA 27 August and 12 August]. On top of that, Oracle blew off a 2 September hearing.

To be reasonable, if you extend a contract for three years, especially given implementation failures at both VA and Oracle, some additional compensation is going to be required and 2018 prices no longer should apply. But the committee members weren’t prepped for the extension nor the increase, and that is both Oracle’s and VA’s unforced error.

Adding to the general agita is the letter sent by The National Association of Veteran Affairs Physicians and Dentists (NAVAPD), a national VA association that represents VA’s 20,000 doctors and dentists, to several House and Senate committees including Veterans Affairs. It recommends that VA halt the entire EHRM rollout until various issues are resolved and goes as far as recommending retaining the venerable VistA, which surprisingly is still running at transitioned medical centers. TTA 5 Nov

Hat tip to a Reader who is familiar with the above matters!

Big Wednesday, vol. 1: Anthropic to price IPO Wednesday, ANT to trade Thursday (updated)

[Editor’s Note: “Big Wednesday” is a cult surfing film directed/written by John Milius from 1979. The surf definitely has changed.]

Anthropic to price out its IPO on Wednesday, go public on Thursday. The price, originally estimated by Mr. Market to be in the $70-78 range, is now rumored to be going higher, based upon what the ‘usual suspects’ are telling CNBC this morning (US ET). The truth, of course, won’t be out until the IPO closes today (Tuesday) at 4pm ET, when total demand is locked in. It’s then expected that ANT will start trading on Nasdaq on Thursday, subject to the usual regulatory approvals. Update: ANT’s shares will debut at $83.

Financial research newsletter SmarterX does a good clean job of summarizing ANT’s facts beyond the haze generated by CEO Dario Amodei [TTA 13 Nov]. FTA:

  • 825 million – Shares in the proposed public offering
  • $70 to $78 – Expected price range per share
  • $64.4 billion – Approximate public offering total at the top of the range [Editor’s calculation: every additional dollar beyond $78 is worth $775 million]
  • $901 billion – Purchase commitments and leases through 2045, some subject to conditions or termination rights

SmarterX also notes the level of risk in the offering. “Anthropic is preparing to sell shares to the public while telling prospective investors that financial returns will not always determine its decisions.” That can be good or bad. As they note, AI bets are made years ahead and there are safety considerations that can change their models. Anthropic is still organized as a public benefit corporation (PBC).

Their ‘what to watch’: “Whether the IPO stays on schedule, and Anthropic stays true to its commitments. Although ANT has already hedged the latter in this Editor’s view, one wonders how it will affect the takeup among institutional investors.

[Editor’s note: None of the above should be construed as investment advice nor as recommendations as to advice providers.]

Another interesting view for our UK and foreign oligarch Readers is a ‘knock-on effect’. Will the Anthropic IPO re-ignite the flailing London luxury real estate market? “According to Coutts, eight in 10 properties in neighbourhoods such as Mayfair, Belgravia and Knightsbridge are selling below asking price, with values across the prime market down between 3% and 6%.” Will the London office’s 200-odd newly minted millionaires and merely affluent re-ignite those neighborhoods? In Mortgage Introducer’s view, the Magic 8-Ball says ‘cloudy’. For expats working at ANT, there’s something called the ‘stamp duty’ that is about 7%. For UK citizens working there, most of their net worth isn’t going to be liquid right away–in other words, it’s on paper, and paper doesn’t translate to assets for a mortgage anytime soon. Conclusion–don’t bet on this right now.

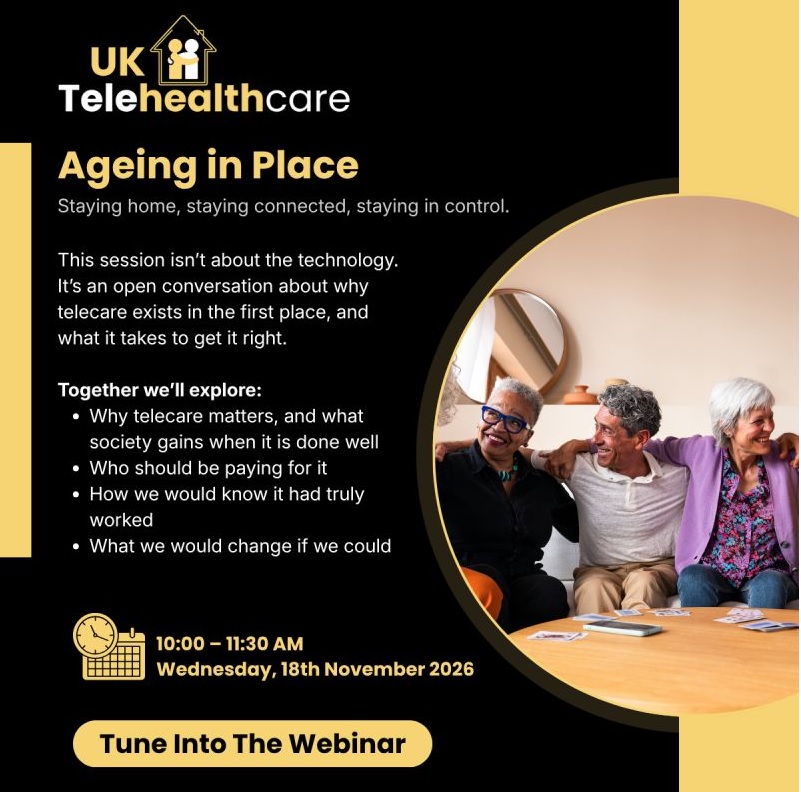
Ageing In Place: UKTelehealthcare webinar Wed 18th 10.00-11.30am GMT

UKTelehealthcare’s upcoming free webinar (Wednesday 18 Nov, 10am GMT) is on Ageing In Place and the role that telecare and technology enabled care systems (TECS) play. From UKTHC’s feature on LinkedIn:

More people want to live independently for longer, and technology enabled care is helping to make that possible.

But this session isn’t about the technology.
It’s an honest conversation about why telecare exists in the first place:
→ What society gains when it’s done well
→ Who should be paying for it
→ How we would know it had worked
→ What we would change if we could

Underneath it all sits the analogue to digital switchover in January 2027. It gives these questions real urgency, because the decisions being made now will shape care for the next decade.

As an independent, member-led organisation, we’re bringing together speakers from across the sector to talk about what matters, not what to buy. No products, no pitches. Just the questions our members tell us they’re wrestling with, and the people best placed to help answer them.

Join the conversation for free 👇 (This is the link to the free Zoom registration)
https://lnkd.in/emGegDNx

TTA’s Wet Autumn Leaves: Jensen Huang slips, Amodei gets ROTFL’d, Oura buys Counsel Health, XRHealth snaps up a few, Charta Health’s $55M raise, more!


13-16 November 2026

A lighter week for traditional news, but it ended in two bombshells. Nvidia honcho Jensen Huang was forced to resign and Anthropic’s Amodei got the ROTFL treatment after promising to end diseases like cancer in less than ten years–in an IPO roadshow video, no less. There was strong M&A action again with Oura snapping up Counsel Health for $625 million, XRHealth snapping up another company, this time with Pear’s addiction tech, and Charta Health’s Series B. But this week’s Must Read is essential to understanding the fog around AI and the tug of war between Doomsters and other factions, all playing with and against each other. “The End of the World…” is long but worth it.

Please feel free to comment on the articles and pass along this Alert. Let me know if this is worth it to you! Also check out my personal page on Substack.

The week that was in AI, more opinions on the Anthropic IPO, and a Must Read on “The End of the World as Business Model” 

M&A/Funding news roundup 11/11: Oura’s big buy of Counsel before IPO, XRHealth buys PursueCare and Living Brain, Charta Health’s $55M Series B

Last week

Weekend Must Reads: Polevikov on Walmart’s Ninth Try At Health with General Medicine, Zitron on the Collapse of the AI Bubble
More questions for Oracle as VA doctors and dentists question EHR rollout safety, demand a pause; Oracle’s $20B AI building raise
Rounding up the funding and M&A action of early Q4–plus CVS’ split, Anthropic’s IPO

More Of Interest 

IPOs, IPOs–Oura’s stalls out, Anthropic’s restarts, possibly mid-November. To everyone’s amazement!

Developing: Walgreens’ Sycamore Partners owner on final approach to sell Boots operation to Canada’s Weston family for ~$9B

Oracle’s continued restructuring cuts 3K more jobs, adds $700 million while revenue grows 30%; House VA Committee subpoenas Ellison, Sicilia 19-0–and why Congress is mad at a 170% budget increase (Updated for how Congress really feels)

AI’s hoofbeats as Horses, not Zebras: a Gimlety view of AI’s destructive capacity (updated) (P(doom) may be conquered by F(doom), or Why Worry?

 * * *
Advertise on Telehealth and Telecare Aware
Support not only a publication but also a well-informed international community.

Contact Editor Donna for more information.

Help Spread the News

Please tell your colleagues about this free news service and, if you have relevant information to share with the rest of the world, please let me know!

Donna Cusano, Editor In Chief
donna.cusano@telecareaware.com

Telehealth & Telecare Aware – covering news on latest developments in telecare, telehealth and eHealth, worldwide.

The week that was in AI, more opinions on the Anthropic IPO, and a Must Read on “The End of the World as Business Model” (updated)

History before our eyes. Or how the mighty can break a leg, and it isn’t over. By now you’ve absorbed another departure from flight, the resignation (read, ouster by the board) of Nvidia co-founder and CEO Jensen Huang. The worst of the revelations was his extra-marital relationship with an alleged Chinese intelligence asset, a certain Alice Huang (no relation; likely this is an anglicized version of a Chinese name). Piling on are allegations of an affair with Nvidia’s VP of healthcare, Kimberly Powell, as well as a third Nvidia employee. Nvidia is probably the most valuable company right now in the world, the 9,000 lb. bull elephant in producing graphics processing units (GPUs), central processing units (CPUs), and artificial intelligence infrastructure software. The company that was born in a Denny’s (a chain diner) that nearly went broke a few times, that was linchpinned by Huang’s marriage to an early microchip designer he met at Oregon State University, now his wife, who now co-controls millions of Nvidia shares in family trusts.

Alice Huang and Megaspeed, a Singapore company, are being investigated by the US Department of Justice (DOJ) on circumventing American export restrictions on advanced AI chips into China, plus reportedly a separate effort to smuggle Super Micro server products with Nvidia chips into China. Huang, a Hong Kong native, was formerly CEO of Megaspeed. Today she was barred from reentering the country over inaccurate information provided to Singapore police. Singapore is reportedly frustrated with the slowness of the US law enforcement response as well. South China Morning Post

Today Nvidia stock bounced around a bit, but it is a company too dominant, too much part of everyday infrastructure and AI, to take much of a hit. For investors, it may be a buying opportunity. The Nvidia board swiftly named an interim CEO, the well-regarded CFO Colette Kress. Yahoo Finance

Updated 18 Nov: Despite calls for Jensen Huang’s reinstatement by Elon Musk and President Donald Trump, the Nvidia board has refused to bring him back, citing its own investigation into his behavior and whether it compromised national security or trade secrets. They have hired Wachtel Lipton to conduct said investigation. CNBC  And the rumor mill is swirling on cui bono, with Anthropic leading the list of Suspects. Huang was an advocate of open-sourced AI, which isn’t in ANT’s or OpenAI’s interest. At all. Short sellers? Congress? Howard Lutnick at Commerce versus Scott Bessent at Treasury over not blacklising Megaspeed? In any case, Senator Tim Scott (R-SC) has requested that both Huang and Lutnick show up before the Senate Committee on Banking, Housing, and Urban Affairs before Christmas leave on 3 and 10 December respectively. Yahoo Finance, Bassell Haidar on LinkedIn

Of course, Mr. Huang retains a considerable number of shares: 800 million to 812 million shares (about 3.4% to 3.5% of the company), most of which are in joint trusts held with Lori Huang. Not inconsiderable, but not the kind of control that Larry Ellison has at Oracle (40%).

Rather harder to believe are the all too expansive blatherings of Anthropic’s CEO Dario Amodei in his IPO roadshow video. This Editor, who comes not only from marketing but also from Startup/Early Stage Health Tech Communications World, is rather inured to “save the world” claims made by CEOs. Fine for the press, but not for the investors; “say it safely”, man! Example: we all made book on (well, some of us hoped) that telehealth and associated healthcare tech would make healthcare more affordable, accessible, and available to all from NYC to Uttar Pradesh. And in large part it’s done so, but it took two decades, a pandemic, a trail of tears, and high profile failures to do it.

So here we have a video with CEO Amodei making this absurd claim: “If today we look at things like cancer, Alzheimer’s, heart disease and mental illness, these will be relics of the past in I think less than a decade.” Can Amodei and Anthropic deliver? Of course not. Anyone in healthcare, not even biotech, would be able to rebut him. Since drug development not only is tied to a long-term clinical timeline and a clinical trial for safety and efficacy framework that could be shortened (good) but also that every one of these diseases is multi-factorial–especially cancer, but also diseases of the brain such as dementia and mental illness (not good)–any claim that any or all of these diseases will be ‘relics of the past’ in 10 years is pure hype. Improving healthcare? Probably. Even the eternal optimist Eric Topol, MD can’t get on board with Amodei. Nor can the chair and CEO of Eli Lilly, Dave Ricks. On X, Amodei was savaged or, less dramatically, ROTFL’d. 

You don’t want to be either before a zillion-dollar IPO.

To say these things in an IPO video is clownish, but also verges on investor fraud. SEC, where are you? 

It definitely takes away from Anthropic’s business case for the public investor, to put it mildly. Constellation Research has a sober take on the IPO, from ‘absurd’ to ‘interesting’; if you like numbers, this is for you. Over on Substack, Marcus on AI lands on the side on the absurd and compares Amodei with Elizabeth Holmes, along with the hindquarter leavings of horses and bulls. In this Editor’s view (in this article’s comments), she expressed the deep desire of Anthropic’s investors to exit as they are so far down the rabbit hole they are looking to tunnel out, thus the urgency to IPO. She also commented on another comment likening tech CEOs to cult leaders, which is a really chilling thought.

Which leads us to this week’s long Must Read, The End of the World as Business Model. It is published on an unlikely platform,  LinkedIn, by an author I haven’t come across before, Joe Lang. It is a finely tuned roundup of the panic around AI and P(doom) ending humanity, which were the hot topics that closed out the summer [TTA 17 Sept]. But it moves on to outline and sledgehammer the contradicting narratives ranging between P(doom) and AI as Mankind’s Savior. It touches on the philosophy, from the neo-paganist (my term) worship of computers, to the ‘singularity’ where man loses control over technology, to ‘effective altruism’ which is a radical form mixing utilitarianism and alleged  rationality, a philosophy that would give Ayn Rand, the ultimate rationalist, indigestion on its premises.

Mr. Lang and I agree that no one is going to stop this freight train, but that we the public should recognize that within the proponents of AI there are different groups pulling our strings and attempting to confuse us: Doomers increasing our fatalism to cover their writing the rules, Accelerationists who point to national interest while they pull up the ladder on small AI, Centrists who want regulation but don’t want Big AI writing the rules, and Believers in the triumph of the singularity. There are too many people within AI ‘high on their own supply’. Real issues get obfuscated: data centers with their huge footprint, energy (acknowledged by Jensen Huang), and water needs, the destruction of jobs ironically in the information sector and management overseeing systems, and very real cognitive decline researched quantitatively among heavy and young AI users. What is inevitable? (F)doom–financial doom–will catch up to many AI companies well before (P)doom. (Whether a failure of Oracle, OpenAI, or even Anthropic will crater the economy scares me more than (P)doom.)

Towards the end, Mr. Lang discusses the difference in using AI as scaffolding or substitution for the thought processes that go into doing the work. Warning: it is a long way to the end of this article, he touches on nearly everything, but ultimately it will be worth your effort. 

M&A/Funding news roundup 11/11: Oura’s big buy of Counsel before IPO, XRHealth buys PursueCare and Living Brain, Charta Health’s $55M Series B

Skipping the IPO, Oura spends $625 million to acquire Counsel Health. Obviously Oura, the health monitoring ring company, has some free cash in the bank because their deal to acquire Counsel was announced to close by end of year–about seven weeks away. What Oura adds with the Counsel buy is an app/AI-driven primary care facilitator that combines medical AI with real live doctors. They also add Counsel’s base in enterprise accounts, which will expand Oura from its individual sales base.  Oura and Counsel have been partnering since the start of this year. When fully integrated, information from the Oura app will ping Counsel’s medical AI chatbot and then can be forwarded to a Counsel Health doctor for follow up.

At $625 million in cash, it’s one heck of a Happy New Year for Boston-based Counsel’s investors: Andreessen Horowitz, Pear VC, Asymmetric Capital Partners, Google Ventures, Floodgate. They only put in $36 million over two rounds (seed, Series A) of funding since 2024 (Crunchbase). Quick M&A turns like this are highly unusual in this market. It’s a big bet for Oura but their last quarter’s revenue grew 153 percent year over year to $533 million and they claim a 16% margin. 

Whether Counsel’s enterprise accounts will support the extra cost for an Oura ring (~$350 plus a $70 yearly subscription) is a legitimate question in pricing. There’s also a Medicare spin. Oura and Counsel will be working together in Medicare’s Part B ACCESS model that started in July. It supports technology-enabled care for chronic conditions, including high blood pressure, chronic MSK pain, and diabetes, for eligible Medicare beneficiaries.

It’s a smart move for Oura. It adds more continuity and completion to their monitoring, creating a full system. That model adds  substantial value–before the IPO that will undoubtedly take place in 2027. Will Oura have success in lowering the cost curve for the enterprise accounts and to sell it more widely–and when will that be? Perhaps this was the reason why Oura delayed the IPO?

What’s not stated in the lengthy release beyond the anodyne welcoming the Counsel team is hard detail on the future of the Counsel operation and their executive group. Oura is based in San Francisco. Mobihealthnews, MedCity News

XRHealth buys PursueCare, entering the addition treatment area. Acquisition cost was not formally disclosed (see below). XRHealth is a telehealth company that offers virtual reality therapy for mental health and pain management. 

PursueCare is a virtual addiction counseling app that targets individuals through health systems and providers. PursueCare also owns three FDA-authorized digital therapeutics, RESET (substance use disorder–SUD), RESET-O (opioid), and RESET-A (alcohol). Here is where it gets interesting. Remember Pear Therapeutics? All three digital therapeutics were part of the Pear bankruptcy ‘estate’. They, along with other Pear assets, were first bought by Pear founder Corey McCann, MD under his company Harvest Care for $2 million, then sold to PursueCare [TTA 31 Oct 2024]. Dr. McCann, now managing partner at T. Rx Capital, is on PursueCare’s board; Harvest Bio is listed as an asset of PursueCare.

Behavioral Health Business put together some XRHealth financials. Crunchbase confirmed a funding round of $2.2 million on 23 October as well as a $43.2 million total funding over 15 (!) early rounds. BHB also sourced from a SEC Form D filing, also on 23 October, that XRHealth, a private company, issued $16.25 million in shares of its common stock to the sellers of PursueCare and Harvest Bio.

XRHealth’s modus operandi is acquisition. Earlier this month, XRHealth acquired Living Brain, a German medical device company that uses extended reality (XR) technology for neurological rehabilitation. In July, XRHealth acquired Swing Therapeutics. Swing Care offers digital therapeutics for chronic pain and fibromyalgia as part of its FDA de novo authorized Stanza program. Again, XR did not announce transaction costs for either acquisition. Mobihealthnews

Charta Health raises $55 million, launches payer platform. The Series B round was led by Insight Partners, with participation from existing investors Madrona, Bain Capital Ventures, South Park Commons, and QuantumLight for a total funding of $85 million in the past two years. Charta is an AI chart review platform that claims 11% revenue uplift by scaling pre-billing chart review across 100% of patient encounters to lessen the endless cycle of claims submissions, denials, and appeals. With the Series B, they launched the Charta for Payers platform for health plans, including six AI-powered modules to improve accuracy and operational efficiencies around medical billing and workflow. The fresh funding will help to expand Charta for Providers to additional medical specialties. Release, Mobihealthnews, Behavioral Health Business

TTA’s Autumn Leaves Pile Up: CVS’ Big Split, Walmart tries a health store again, that AI bubble looks thin, Oracle’s many question not just with the VA, funding action + Anthropic’s IPO, more!

6 November 2026

We’re BAAAAK! After travel, colds, technical difficulties and all. Walmart tries, tries again in the healthcare space with a third-party online store, the thinning of the AI bubble, the many questions around Oracle with the VA as well as data center financing, and The Big Roundup of Q4 Financings, including the CVS split and Anthropic’s IPO.

Please feel free to comment on the articles and pass along this Alert. Let me know if this is worth it to you! Also check out my personal page on Substack.

Weekend Must Reads: Polevikov on Walmart’s Ninth Try At Health with General Medicine, Zitron on the Collapse of the AI Bubble
More questions for Oracle as VA doctors and dentists question EHR rollout safety, demand a pause; Oracle’s $20B AI building raise
Rounding up the funding and M&A action of early Q4–plus CVS’ split, Anthropic’s IPO

More Of Interest 

IPOs, IPOs–Oura’s stalls out, Anthropic’s restarts, possibly mid-November. To everyone’s amazement!

Developing: Walgreens’ Sycamore Partners owner on final approach to sell Boots operation to Canada’s Weston family for ~$9B

Perspectives: What Meta’s settlement reveals about youth mental health, access shortages, and where telehealth can support pediatricians

Oracle’s continued restructuring cuts 3K more jobs, adds $700 million while revenue grows 30%; House VA Committee subpoenas Ellison, Sicilia 19-0–and why Congress is mad at a 170% budget increase (Updated for how Congress really feels)

(Related) Revealed: Oracle’s extended VA EHRM contract increased by $17B as original ceiling reached this year; VA Indy EHR goes online

AI’s hoofbeats as Horses, not Zebras: a Gimlety view of AI’s destructive capacity (updated) (P(doom) may be conquered by F(doom), or Why Worry?

 * * *
Advertise on Telehealth and Telecare Aware
Support not only a publication but also a well-informed international community.

Contact Editor Donna for more information.

Help Spread the News

Please tell your colleagues about this free news service and, if you have relevant information to share with the rest of the world, please let me know!

Donna Cusano, Editor In Chief
donna.cusano@telecareaware.com

Telehealth & Telecare Aware – covering news on latest developments in telecare, telehealth and eHealth, worldwide.

Weekend Must Reads: Polevikov on Walmart’s Ninth Try At Health with General Medicine, Zitron on the Collapse of the AI Bubble

Two short takes on two Must Reads to make time for this weekend. Neither are short and both are dense. Likely like you, I won’t be reading either at one sitting. But you should put them on the pile.

Walmart Has Failed at Healthcare 8 Times. Now It’s Trying for a 9th. Author: Sergei Polevikov, AI Health Uncut

Sergei ‘goes there’ again with a little-noted move by Walmart to kickstart something significant in the healthcare area. It has inked a deal with TJ Parker, the co-founder of PillPack (sold to Amazon), now CEO of General Medicine, to integrate the General Medicine ‘everyday healthcare store” with Walmart’s Better Care Services, its online healthcare hub. The store comprises not only pharmacy and low cost options for medications, but also specialty care referrals and online everyday testing. You can compare prices online. Walmart release

Readers will remember the eight times previously that Walmart Health, in various and telehealth iterations, collapsed into a heap with the most recent here [TTA 30 Apr 2024, 2 July 2024]. Will this be different? It might, as the heavy lifting is done by General Medicine. 

Of course, the price comparisons, particularly for branded medications, may not be as cheap as expected, but the prices may beat other retail comparison sites. I did some comparing of my own with a medication I am moving to that is not covered by my insurance. The company direct program price for 90 days is less than half of what is on offer with GM. But I had to get the referral from my physician after making my own case that the generic was possibly creating problems for me AND the most popular generic that I was on had a recent recall for sub-potency issues.

The article is available in part to non-paid subscribers. But this Editor recommends you do. Sergei is an unbought investigator in the healthcare field, and provides us with a service that is unavailable elsewhere–even here because we’re primarily a news site. It’s worth your spend because he’s the only one I think of, the ‘go to’, who marshals the numbers and puts together a credible narrative.

FYI you can meet Sergei at HLTH coming up next week. Details are in the article.

Running Dry. Author, Ed Zitron, Where’s Your Ed At?

Ed’s scathing takes on the business of AI are well known to our Readers. In this article, he goes into the fault lines that are widening with AI–and how the money spigots are starting to shut. What does that mean for Anthropic, OpenAI, and healthcare companies like Oracle? What does that mean for our Readers’ suppliers or startups?  As usual, not an easy or quick cuppa read.

He opens with:

As I’ve said for a while, all of this ends when the money runs out — when seemingly-unlimited data center debt becomes distressingly hard to raise, and when AI startups can’t rely on the perpetual availability of venture capital to keep them alive.

And it appears the well is running dry, just as it dawns on everyone that the underlying economics of AI, for labs and data center operators alike, don’t really make sense.

What is really going on with OpenAI when it puts off its IPO, and raises only one-third ($11 billion) of what it hoped for last week? What is really happening with Anthropic, rushing to an IPO but with clear evidence of slowing business and millstones of liabilities? TTA 5 Nov

“The bubble bursts when the money runs out.”  AI is no exception to any kind of startup, from telehealth, RPM, health IT, telecom, deregulated airlines, and tulips. 

And another worthwhile subscription (on sale today!)


More questions for Oracle as VA doctors and dentists question EHR rollout safety, demand a pause; Oracle’s $20B AI building raise

A surprise development not making the VA nor Oracle happy–and another monkey wrench for the committees. The National Association of Veteran Affairs Physicians and Dentists (NAVAPD), a national VA association that represents VA’s 20,000 doctors and dentists, sent a letter in mid-October to chairs and ranking members of the House and the Senate Veterans’ Affairs, Appropriations, Oversight and Government Reform and Homeland Security and Governmental Affairs panels. It recommends that the Oracle Health EHR rollout be paused until “critical concerns about patient safety, system performance, cost, and long-term feasibility are independently evaluated”.  In addition, they cite concerns involving clinical workflow disruptions, delayed referrals, patient safety incidents, and rising program costs.

The letter, disclosed on 29 October, specifies that actions be taken by the committees before deployments continue:

  • Pause further deployments: Suspend additional Oracle EHR implementations while continuing to fund patient care, system maintenance, and the correction of safety problems at existing sites.
  • Require an independent safety assessment: Evaluate patient safety and operational readiness at facilities already using the system, with meaningful input from frontline physicians, dentists, and nurses.
  • Strengthen transparency and accountability: Require regular reporting of patient safety incidents associated with the system.
  • Evaluate alternatives: Conduct an independent comparison of the costs, risks, and feasibility of continuing the Oracle program versus modernizing the VA’s existing Veterans Health Information Systems and Technology Architecture (VistA), including the potential use of AI-assisted software development tools.
  • Increase financial oversight: Require additional documentation and justification of proposed contract cost increases.

Surprisingly, the full text letter states that that the venerable VistA EHR still runs at all of VA’s 170 medical centers—including the sites transitioned over to the Oracle EHR. VistA is still used for longitudinal chart review. The letter also states that VistA is “currently best suited to meet our institutional mission.” which is not exactly a ringing endorsement of change. The dislike of a new EHR runs deep in this group but the workflow flaws are still many in the Oracle system. Another small surprise in the letter is this statement: “One recent analysis, which incorporates AI coding capabilities, estimates that modernization and maintenance of VistA would cost $1–2 billion over the next decade.” This is a group very much advocating continuing to use VistA with bolt-on, AI build/assisted software.

Even without this, it is already leading to a situation where VA clinicians use two EHRs for different purposes that don’t speak to each other.  Which wasn’t the intent.

A response was requested by 23 October. That was not disclosed.

The NAVAPD summary and full text letter to the committees. NextGov  Hat tip to our anonymous ‘eye on VA’.

So where is VA and Oracle now? The Oracle system has been rolled out to only 19 of 170 medical centers and associated clinics. The 2026 portion has ended with go-lives 24 October in the Alaska VA Healthcare System and the Louis Stokes Cleveland VA Medical Center. The Cerner, then Oracle rollout started disastrously in 2022. VA has also requested a $17 billion increase in budget for Oracle’s EHR development, from the original $10 billion, to cover both current costs and the three-year extension to May 2031 in the 2027 Military Construction, Veterans Affairs, and Related Agencies Appropriations Act. Both Mike Sicilia and the mighty Larry Ellison have been subpoenaed and have agreed to appear before both House and Senate committees on 19 November and 10 December, respectively. TTA 17 Sept

Oracle raised $20 billion for its AI data center plans in the past two weeks. In its new role as Data Center Builder and Landlord, Oracle’s raise consisted of “concurrent offerings of US$10b in common stock and US$10b in senior notes to fund heavy AI and cloud infrastructure spending. This included multiple tranches of fixed rate, senior, unsecured bonds with coupons between 7% and 8.65% and a US$10b equity sale at US$116 per share.” The further analysis in Yahoo Finance from Simply Wall St isn’t simple but comes down hard on the risk that Oracle is taking on the buildouts, “You have to believe its huge AI and cloud buildout converts a US$638b backlog and multicloud database momentum into durable, cash generative usage.”  Most of Oracle’s contracts are with OpenAI. Meaning that if AI demand trails off, or (as Ed Zitron has opined) if OpenAI goes bust, Oracle is in trouble plenty [TTA 19 Aug].

Rounding up the funding and M&A action of early Q4–plus CVS’ split, Anthropic’s IPO

Your Editor has returned after a fair amount of travel away from the desk. She was also sidelined to attend to some health issues, including a nasty cold that hasn’t quite taken its claws out of her head and lungs yet, and some technical difficulties on our publishing site.

The big news today is CVS’ split that undoes their ‘big bang’ of 2018. Unusually, there’s a lot of early Q4 investment at the Series A level and a bit of M&A action. In AI World, Anthropic finally filed for their IPO while OpenAI is asking for more bridge money. Here’s our selective roundup:

  • Today’s bombshell was that CVS is splitting its lines of business into two publicly traded companies by H1 2028. The first new company will be CVS Health, consisting of Aetna and Caremark, the CVS pharmacy benefit manager (PBM), Oak Street Health, home health firm Signify Health and CVS’ specialty drug business. The second will be CVS Pharmacy, containing roughly 9,000 retail stores and pharmacies, plus the mail order pharmacy, walk-in clinics and Health100 technology services. According to CNBC, CVS Health will be run by current CEO David Joyner, while CVS Pharmacy will be led by Prem Shah, group president of CVS Health. Other executive assignments are TBD. The company’s market value is about $117 billion. Current shareholders will receive shares in both companies. Healthcare Dive

Both companies have done well in recent quarters, so perhaps this was the time to execute a plan that’s been an open secret for awhile. Will it resolve the charges of conflict of interest made against CVS, with the second-largest PBM? Questionable, as the reorganization places specialty drug alongside the Caremark PBM.

We note that the Merlo/Bertolini vision of an integrated healthcare giant lasted exactly ten years–and that Mark Bertolini now heads up Oscar Health, exactly the opposite of a CVS.

  • In late October, Vera Health raised $28.5 million in Series A funding to expand its evidence-based AI clinical search platform. It’s a word-of-mouth story, as it’s accumulated a claimed 800,000 clinicians using it worldwide from a few thousand a year ago. It’s now used across 190 countries, including approximately 1 in 4 physicians in Spain and Italy and 1 in 7 in France. Vera managed to do this with just 12 employees. The Series A was led by Threshold Ventures, with participation from Mantis VC and SV Angel. Existing investors Y Combinator and Gradient tripled down, bringing the company’s total funding to $32 million. Website/release, HIStalk, PYMNTS.com
  • Tegria acquired CloudWave for an undisclosed amount. Tegria is a global healthcare consulting and IT services company that partners with provider and payer organizations. CloudWave is a full-service cybersecurity and cloud services provider for community hospitals and health systems. Release
  • Administrative automation platform ClarityCare raised $16.5 million in a Series A funding, led by global venture capital firm Headline. New investors were Arthur Ventures and FJ Labs and existing investors were Maverick, firstminute, Top Harvest Capital, and Transpose Platform for a total funding of $20 million. According to their very flashy website, they run AI agents inside health plans, payers and TPAs to automate the administrative and clinical work needed to run cost containment operations. Spurring the funding is the CMS Rule CMS-0057-F which mandates a prior authorization decision timeframe of 72 hours for expedited requests, and seven days for standard requests.  Website/release, MedCityNews
  • Midstream Health garnered $20 million in a Series A for its autonomous financial operations platform. This round was led by Valtruis, and included participation from Andreessen Horowitz (a16z), Foundry and CommonSpirit Ventures. Its network covers over 250 hospitals nationwide and emphasizes recovery via monitoring of contracts, claims, rebates, other supply chain areas,  and payments. Release, MedCityNews
  • And closing today’s roundup, Anthropic PBC, which markets its AI tools as Claude, finally filed its SEC Form S-1 to go public on the Nasdaq, trading under ANT. No target date is given, nor pricing and number of shares. The company is presently closely held by founders Dario and Daniela Amodei. Anthropic’s revenue was $16.3 billion for the first six months of 2026, up 1,300% from $1.2 billion during the same period last year. It all looks lovely except that on-balance sheet liabilites total around $117.5 billion (balanced against roughly $112 billion in cash prior to its IPO). Bloomberg Tax and off balance sheet and long-term compute commitments of $895.4 billion. CNBC, Mobihealthnews

Given all this, the Anthropic IPO may not happen until 2027.

Filing for an IPO does not mean it will happen–see Oura. For instance, OpenAI filed initial SEC forms in June, but is delaying their IPO to sometime in 2027. They are currently seeking a bridge raise of $10 to $20 billion this year in advance of the IPO. FT. The WSJ reported that they have subscribers for about $11 billion of this. 

TTA’s Autumn Leaves: Oura puts off IPO, Anthropic’s IPO November (?); Sycamore Partners nearing Boots sale; telehealth support for pediatricians in youth mental health, Oracle’s Congressional spanking, more!


2-5 October 2026

Here we are past the first week of Fall (or Autumn). The leaves may be turning, but the healthcare/AI  IPOs aren’t, with the Oura health monitoring ring postponing its IPO indefinitely and the Anthropic AI rumored only for early-to-mid-November. Another turning is for Boots, with Sycamore Partners breaking up the Walgreens Boots Alliance combine for $9 billion. And this week’s Perspectives discusses the burden pediatricians are taking on in youth mental health and how telehealth can support this need.

For Readers: Your Editor will be on publishing leave due to travel to 21 October. ‘Best Of’ Alerts will be out weekly on Fridays and Saturdays after this week till then. Some past highlights:

  • Humanity’s Rumored Doom in 10 years at the hands of AI are Zebras, not Horses.
  • Oracle’s simultaneous strong Q1, 3,000 layoffs, and its two top execs subpoenaed by the House VA Committee for a whacking over the 170% increase in budget to cover the next three years (Congress is Fed Up).
  • How infrastructure tech needed by healthcare organizations can’t get arrested on funding, while whiz-bang consumer apps can.

Please feel free to comment on the articles and pass along this Alert. Let me know if this is worth it to you! Also check out my personal page on Substack.

IPOs, IPOs–Oura’s stalls out, Anthropic’s restarts, possibly mid-November. To everyone’s amazement!

Developing: Walgreens’ Sycamore Partners owner on final approach to sell Boots operation to Canada’s Weston family for ~$9B

Perspectives: What Meta’s settlement reveals about youth mental health, access shortages, and where telehealth can support pediatricians

More of Interest 

Oracle’s continued restructuring cuts 3K more jobs, adds $700 million while revenue grows 30%; House VA Committee subpoenas Ellison, Sicilia 19-0–and why Congress is mad at a 170% budget increase (Updated for how Congress really feels)

(Related) Revealed: Oracle’s extended VA EHRM contract increased by $17B as original ceiling reached this year; VA Indy EHR goes online

AI’s hoofbeats as Horses, not Zebras: a Gimlety view of AI’s destructive capacity (updated) (P(doom) may be conquered by F(doom), or Why Worry?

Perspectives: Digital Health Capital Keeps Rewarding What Patients See, Not What Keeps Companies Alive (Infrastructure tech can’t get funding)

Silicon Valley Bank’s take on H1 investment: among the “have and have nots”, it was “the best half in years” for health tech

 * * *
Advertise on Telehealth and Telecare Aware
Support not only a publication but also a well-informed international community.

Contact Editor Donna for more information.

Help Spread the News

Please tell your colleagues about this free news service and, if you have relevant information to share with the rest of the world, please let me know!

Donna Cusano, Editor In Chief
donna.cusano@telecareaware.com

Telehealth & Telecare Aware – covering news on latest developments in telecare, telehealth and eHealth, worldwide.